How we supported a fruit processing and packing facility with Capital Allowances
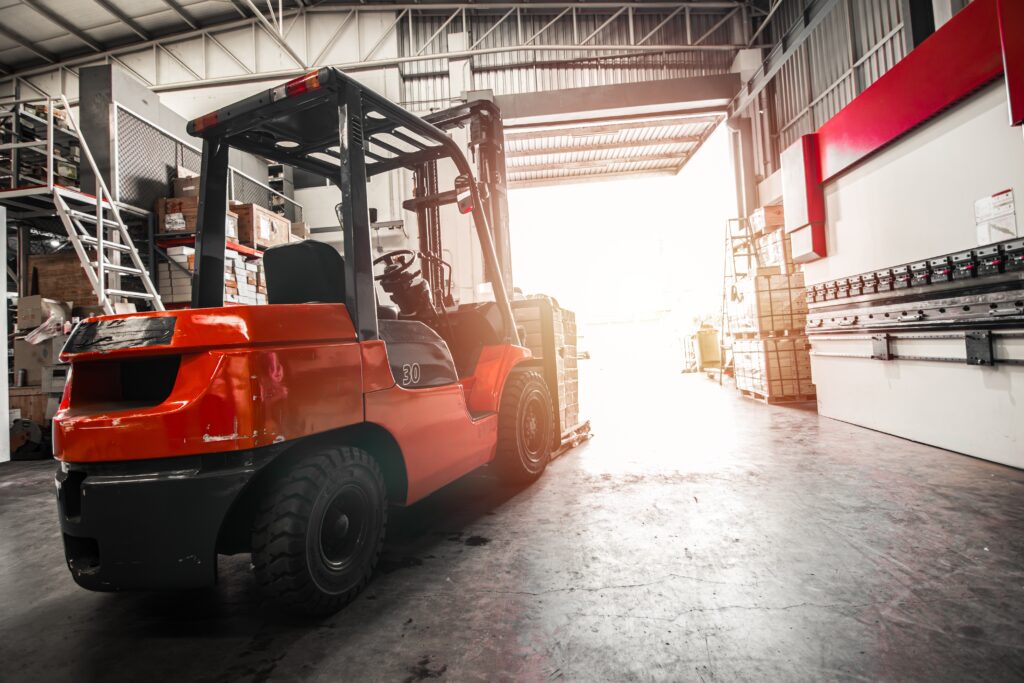
Our client took a lease on a warehouse property that had previously been used for the same trade. The site comprised offices, chilled storage, ripening, packing and distribution facilities.
Following acquisition of the lease, the client immediately embarked on a major refurbishment programme with an estimated outturn cost of circa £14m.
Managing the project in-house, the client engaged a wide range of trade and specialist contractors and suppliers. At the client’s financial year end, the project remained ongoing, with approximately £9.5m of expenditure incurred.
Recognising the significant capital investment involved, we were engaged at an early stage of the project. This enabled us to:
- Liaise directly with contractors and suppliers to obtain additional information where required.
- Undertake site visits during the refurbishment works to gain a detailed understanding of the alterations being carried out.
- Provide robust capital allowances estimates to support quarterly tax payments and wider tax planning.
Key findings
Our interim report, based on £9.5m of incurred expenditure, identified:
- Main Rate Pool: £5.25m
- Special Rate Pool: £1.2m
- Land Remediation Relief: £0.2m
- Repair Works (Revenue): £1.25m
How specialist input enhanced the claim
A detailed survey of the property, combined with a thorough review of specifications, drawings and cost information, enabled us to identify and capture all qualifying expenditure. Where costs were not separately identified or available, we prepared estimates based on first principles.
We also considered and appropriately apportioned time-related costs, including contractors’ preliminaries, acceleration payments, overheads and profit, together with relevant professional fees.
As the expenditure related to an existing building, a number of specific capital allowances considerations applied, including:
- CAA2001 s25 works incidental to the installation of plant and machinery.
- Thermal insulation to an existing building.
- Expenditure on repairs and maintenance works.
In addition, the client’s trade and operational requirements created further opportunities to maximise available relief. These included expenditure relating to:
- Hygienic and specialist floor, wall and ceiling finishes.
- Insulated walls and ceilings creating refrigerated cold rooms and stores.
- Dock levellers and certain doors.
- Mezzanine structures.
- Builders’ works incidental to the installation of qualifying plant and equipment.
Our review also ensured the correct allocation of expenditure between the relevant tax treatment categories, including:
- Identifying works that should be treated as revenue expenditure on repairs to the building.
- Quantifying expenditure on asbestos remediation qualifying for 150% tax relief.
- Analysing contractors’ costs in detail to allocate expenditure to the Main Rate Pool (Full Expensing) that might otherwise have been included within the Special Rate Pool. Examples included electrical works relating to fire alarms, access control systems, CCTV and intruder alarms.
The outcome
The tax saving associated with our support is £2m, with the majority available in the year the expenditure was incurred. This represents a very significant reduction in the overall cost of the refurbishment project and demonstrates the value of specialist capital allowances advice being introduced early in the lifecycle of a major property investment.
If you would like to find out more about Capital Allowances and how we can support you, please contact us.